Services

Scheme fee solutions for card issuers.

We work for card issuers, BIN sponsors and fintechs. The scope and fee are agreed before we start, and every engagement ends with something your team can use.

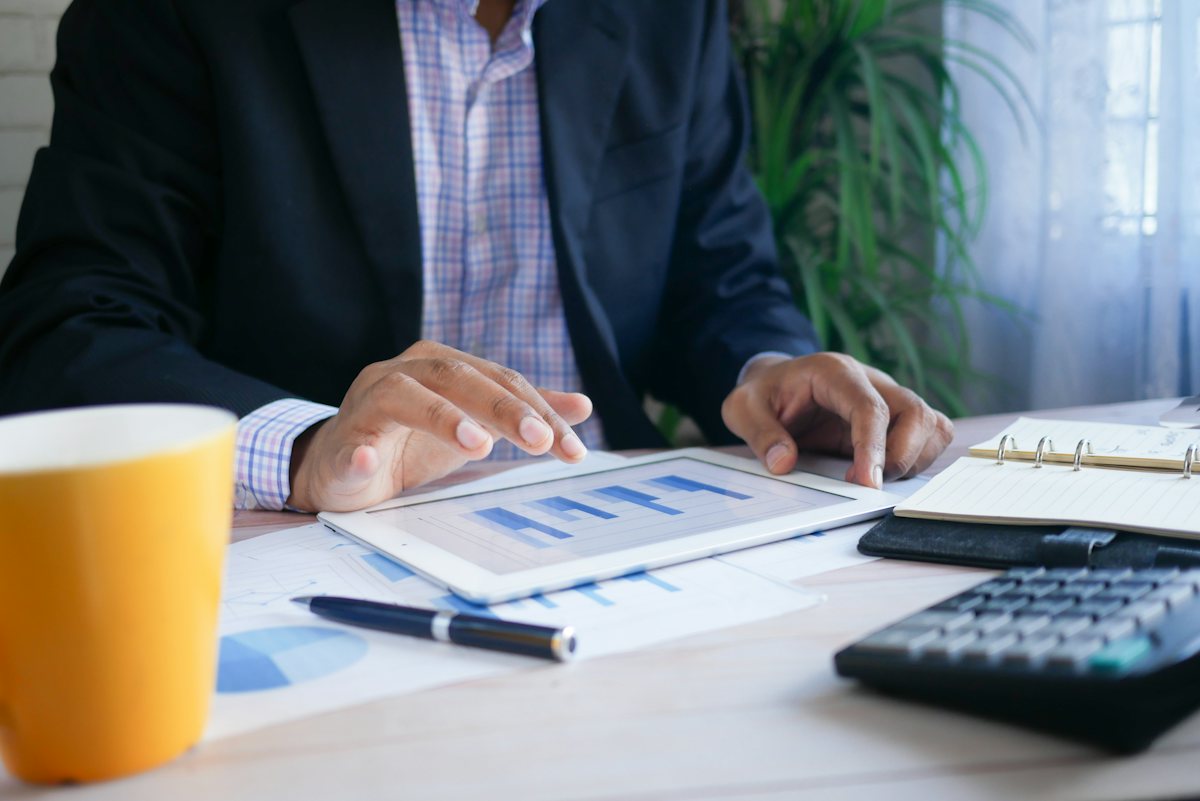
A person at a desk checking figures on a tablet, with a calculator and printed charts beside them

Scheme fees

Scheme fee review

We read your Visa and Mastercard invoices line by line, and show which fees are wrong, unused or avoidable, with the yearly cost of each and the action that stops it.

Schemes
Visa, Mastercard, or both in one review
Period
Your choice, from a few months to several years
You send
Invoices and billing files, with no card numbers
Fee
Agreed with you before work starts

What you get

  • A written report, with findings ranked by saving
  • The invoice lines and guide entries behind every finding
  • A call to walk your team through the report
  • If you opt in, access to our fee portal to follow your fees over time

Fee lines, Mastercard

Example
Fee lineAprMayCheck
Issuer authorization€4,120€4,236In line
Monthly subscription, 2RP5061€600€1,200Doubled
Issuer cross-border€2,980€3,050In line
BIN fees, range with no cards€150€150No activity
Illustrative figures.

Portal

Scheme fee portal

A secure portal where your team analyzes its Visa and Mastercard invoices. Its tools help you investigate any fee line and spot anomalies, such as a fee that jumps, repeats or no longer matches its rate.

Schemes
Visa, Mastercard, or both
Access
Secure logins for your team
Fee
Agreed with you before you start

What it helps you do

  • See all your invoice lines in one place, across schemes and periods
  • Investigate any fee line: filter, sort and compare it across periods
  • Spot anomalies, like fees that jump, repeat or change rate
  • Keep your review findings next to the fees they concern

Scheme fees, explained

Scheme fees are what Visa and Mastercard charge issuers and acquirers to use their networks. In the US they are called network fees. They are a separate cost from interchange and from what you pay your processor.

Regulators are paying attention. The UK Payment Systems Regulator found that Mastercard and Visa raised their core scheme and processing fees to acquirers by at least 25% since 2017 (PSR, 2025). Australia's central bank calls scheme fees "opaque and complex" (RBA, 2026).

How they are billed
Every fee arrives as a coded line on the scheme's invoice, with a billing event, a quantity and a rate. The invoices run to many pages, so few teams check them line by line.
What they charge for
Some fees follow your volumes: transactions, cards and amounts. Others are fixed, like license and BIN fees. On top come optional services, such as reports and fraud tools, and fees for how transactions are sent.
Why they keep growing
The schemes add fees and change existing ones through regular announcements. Optional services are easy to switch on and rarely switched off, and BINs that stop carrying traffic can keep their fees. Each change is small, so the total grows without anyone deciding it should.
What they are not
Interchange moves between the issuer and the acquirer on each transaction. Processor fees go to the company that runs your card platform. A review looks only at what you pay Visa and Mastercard.

Questions

Questions we get

Do you need access to our systems?

No. We work from the invoices and billing files you send us, which carry no card numbers.

What do you need from our team?

The invoices for the scheme you want reviewed, and a few answers about the optional services you pay for.

Which schemes do you cover?

Visa and Mastercard. We review one of them or both together, over the period you choose.

What does a review cost?

It depends on the size of your invoices. We agree the fee with you before any work starts.

What happens after the report?

Your team makes the changes with the scheme, and we stay available to explain any finding. If you opt in, you keep access to our fee portal to follow your fees over time.

Are scheme fees and network fees the same thing?

Yes. Scheme fees is the usual name in Europe and many other regions, and network fees is the name in the US. Both mean the fees Visa and Mastercard charge issuers and acquirers to use their networks.

Who is a review for?

Card issuers, BIN sponsors and fintechs that pay Visa or Mastercard fees, directly or through a sponsor. Credit, debit, prepaid and commercial programs all pay them.

How long does a review take?

We agree a date for the report before work starts. It depends on how many invoices, BINs and ICAs are in scope.

Do you work with issuers outside the US?

Yes. We work remotely with clients in any country. The schemes bill the same way everywhere, though fees and rates differ by region.

Do you also look at interchange or processor fees?

No. A review covers what you pay Visa and Mastercard. Interchange and processor fees are separate costs, set by separate agreements.

Start with a short message.

Tell us which scheme you want reviewed. We reply by email with the next steps and an NDA.